Accounting
-

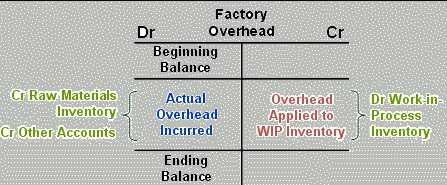
Basic Objective For Accumulating Actual Factory Overhead
ACTUAL FACTORY OVERHEAD : Estimating the factory overhead, deciding upon the base and activity level to be utilized, and calculating…
Read More » -
How To Calculate Manufacturing Overhead Rate Per Machine Hour
The following system is presented to focus on How to Calculate Overhead Rate or calculate Factory Overhead per Machine Hour…
Read More » -
Absorption Costing And Variable Costing Methods
Absorption costing and variable costing methods: Inclusion or Exclusion of Fixed Overhead Items to Products-> Ordinarily, cost accounting procedures apply…
Read More » -
Expected Actual Capacity As The Level Of Capacity Utilization
Expected Actual capacity utilization : The short-range or short-term planning and control approach, or expected actual capacity utilization concept, advocates…
Read More » -
Capacity Management: Normal Capacity Vs. Expected Actual Capacity
Between Normal Capacity Utilization and Expected Actual Capacity Utilization which Activity Level to Be Used for Capacity Management? In calculating…
Read More » -
Overhead Allocation: Direct Labor Hours Vs Machine Hours
Overhead Allocation Debate Direct Labor Hours vs Machine Hours -which one is best overhead allocation base? Answer may vary based…
Read More » -
Basis For Overhead Allocation: Materials Or Direct Labor?
This method has only limited use because in most cases no logical relationship exists between the direct materials cost of…
Read More » -
Overhead Allocation: Units of Production Basis
Units of Production Basis: The units of production basis is the simplest and most direct method of applying factory overhead.…
Read More » -
Basis For Allocating Overhead Costs To Products
Basis for Allocating Overhead Costs: The primary objective in selecting a base is to insure the most accurate application of…
Read More » -
Use Of Predetermined Manufacturing Overhead Rate
The Use of a Predetermined Manufacturing Overhead Rate: A Predetermined Manufacturing overhead rate is used for both job costing and…
Read More »