Accounting
-

What concept in the Conceptual Framework the IASB have looked to with regard to accounting for gold and silver production?
What is the accounting for gold and silver production? Did you ever think? Is it different from other Accounting! Let…
Read More » -
Difference Between Financial And Physical Capital Maintenance
Financial and Physical Capital Maintenance concept and their implications: A financial capital maintenance concept of capital means when the capital…
Read More » -
What is Equity ? Why the Conceptual Framework does not prescribe any recognition criteria for equity.
What is Equity : The C0ncptual Framework defines equity as ‘the residual interest in the assets of the entity after…
Read More » -
Difference Between Income Revenue And Gains
Difference between Income Revenue and Gains Difference between income revenue and gains should be well understood by the accountants. The…
Read More » -
Income Recognition Principle: Fair Value Of Land
Income Recognition Principle: Do You Think The Fair Value Of The Land Is Income To The Company? The fair value…
Read More » -
Characteristics Of A Liability As Per Conceptual Framework
Essential characteristics of a liability : A liability is defined in the current Conceptual Framework as ‘a present obligation of…
Read More » -
Importance Of The Going Concern Assumption In Accounting
Under the going concern assumption or otherwise going concern concept, an entity will continue its business operation for an indefinite…
Read More » -
Enhancing Qualitative Characteristics Of Financial Information
There are two important Qualitative Characteristics Of Financial Information such as Relevance and Faithful Representation. Beside these, the Conceptual Framework…
Read More » -
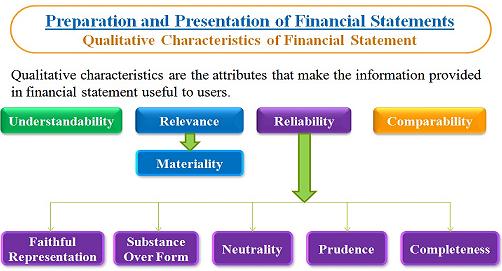
Qualitative Characteristics Of Financial Information
Accounting information should be user friendly. It must me trustworthy and reliable. Materiality is also an important concept. Materiality is…
Read More » -
Objectives Of General Purpose Financial Reporting
Objectives of general purpose financial reporting : Paragraph OB2 of the IASB Conceptual Framework states The objectives of general purpose…
Read More »