Accounting
-

Tax loss accounting treatment, how tax loss is accounted for?|
Tax losses are created when allowable deductions exceed taxable income. The accounting standard envisages that there are three possible treatments…
Read More » -
Recognition Of Deferred Tax Asset And Deferred Tax Liability
Criteria for Recognition of deferred tax asset and deferred tax liability is set under IAS 12. Deferred tax liabilities must…
Read More » -
How accounting profit and taxable profit differ in accounting for income taxes.
Accounting profit and taxable profit differ in accounting for income taxes in the following ways: Accounting profit is defined in…
Read More » -
What is a temporary difference in deferred tax calculation?
Deferred tax calculation Temporary differences between accounting profit and taxable profit arise when revenues and expenses are recognized in different…
Read More » -
The Main Principle Of Tax Effect Accounting As Per IAS 12
Main principle of tax effect accounting as per IAS 12: As the objective paragraph of IAS 12 points out the…
Read More » -
Recognition And Measurement Of Net Defined Benefit Liability
Measurement of net defined benefit liability : The economic substance of the entity’s exposure may be considered as the net…
Read More » -
When Would Contingent Liabilities Become Provisions
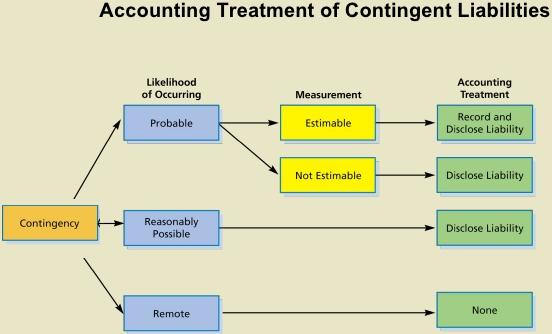
Meaning of Contingent Liability : Contingent liabilities are such type of liabilities or a potential losses that may occur in…
Read More » -
What Is A Constructive Obligation And A Present Obligation?
Constructive obligation One of the essential characteristics of a liability is that there must be a present obligation arising from…
Read More » -
What Are The Characteristics Of A Provision
Characteristics of a provision? The characteristics of a provision are that it is a liability where there is uncertainty as…
Read More » -
What is contingency and contingent liability?
Contingency and contingent liability : A contingency is not defined in IAS 37. In plain English a contingency is an…
Read More »